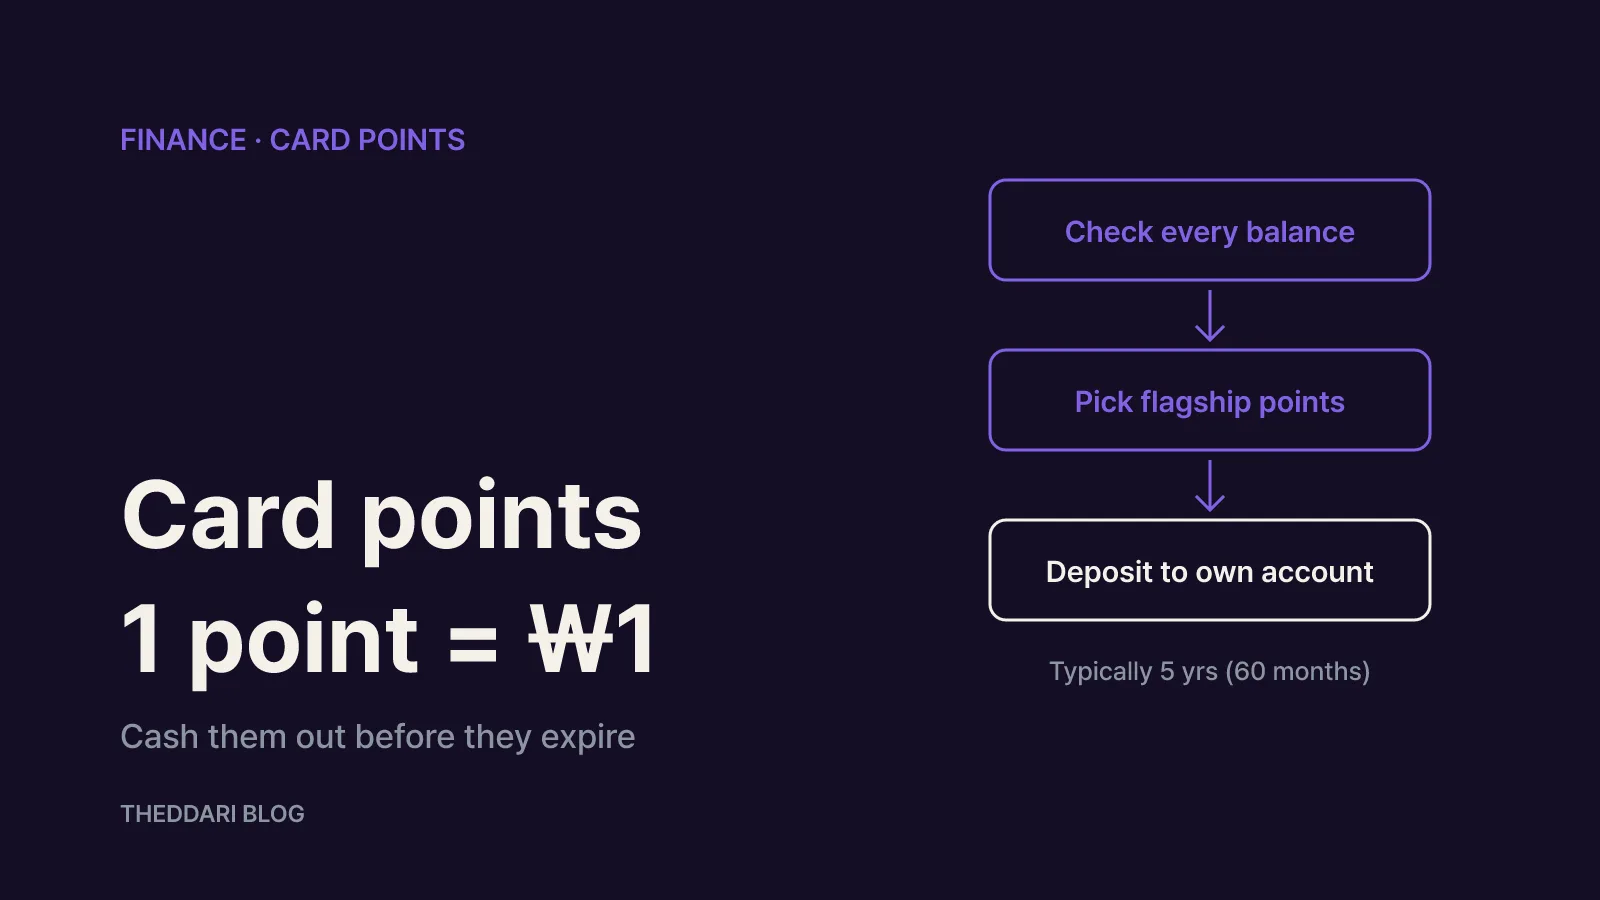
As of November 2026, anyone holding a personal credit or debit card from a Korean issuer can check all of their card points in one place and move the convertible ones into their own bank account at a rate of 1 point = ₩1, starting from a single point. The free service is the Card Point integrated inquiry and account deposit service run by the Credit Finance Association (CREFIA, 여신금융협회). Points typically expire after five years (60 months), but some programs expire after one to three years, so the expiry month shown on screen matters more than any rule of thumb.
This guide is built from CREFIA's official FAQ, a Financial Services Commission (FSC) press release on the cash-out service, and the standard personal credit card terms published by the Financial Supervisory Service (FSS). Issuer-specific details can change, so glance at the on-screen notices before you submit a request.
Who can use Korea's card point portal and what it shows
The service is open to individual cardholders of Korean card companies, including foreigners. Corporate cardholders cannot use it. That makes it one of the simpler money chores for expats and long-term residents who have collected points on cards they no longer carry.
You can access it on the website (www.cardpoint.or.kr), the mobile site (m.cardpoint.or.kr) or an Android-only app called 카드포인트조회. After agreeing to the terms and privacy notices, you verify your identity by mobile phone, card or i-PIN. You may use it as a guest without creating an account. Members can look up balances later without re-verifying, but every cash-out still requires an extra identity check.
For each card company, the results show three things:
- your remaining point balance
- the amount of points scheduled to expire
- the month in which they will expire
Lookups are available around the clock. Some partner points may not appear in the results at all, so if you know you hold points with a co-branded program, check the issuer's own app as well.
There is a second door. The Korea Financial Telecommunications & Clearings Institute's AccountInfo (어카운트인포) app also lets you check and cash out card points. The FSC press release suggests AccountInfo for people who already hold a financial-sector certificate or biometric login, and the CREFIA portal for everyone else. AccountInfo also surfaces long-unused bank accounts, which is handy if you are tidying up several banks at once.
Which points convert to cash
Only each issuer's flagship (representative) points can be deposited. The FSC defines these as points that are not tied to particular partner merchants and can be exchanged with cash 1:1. Partner points, which are limited to specific merchants and carry no guaranteed 1:1 value, are excluded.
CREFIA lists the eligible programs as follows:
← Swipe to see more
| Issuer | Flagship points |
|---|---|
| Lotte Card | L.POINT |
| BC Card | TOP Point |
| Samsung Card | Bonus Point |
| Shinhan Card | MyShinhan Point |
| Woori Card | WiBee WON Kkulmoney / Moa Point |
| Hana Card | Hana Money |
| Hyundai Card | H-Coin |
| KB Kookmin Card | Pointree |
| NH NongHyup Card | NH Point |
| Citi Card | Citi Point |
| Korea Post | Post Point |
Hana Card's Yes, Hana and Hana Members points are combined and appear as Hana Money. Hyundai Card's M Points are not directly eligible: you first convert them to H-Coin on the web, in the app or through the call center, at 1 M Point = 2/3 H-Coin, so three M Points become two H-Coin. Decide whether that haircut is worth it before converting.
For any other program, CREFIA says contractual arrangements with partners make direct cash-out difficult, so ask the issuer how those points can be used. One useful protection: Article 15 of the standard card terms bars issuers from limiting the share of a purchase you can pay with points.
How to request a deposit and when the money arrives
The flow takes a few minutes: open the inquiry and deposit menu, consent and verify, review the cash-out-eligible points for each issuer, enter the amount and your bank account, pass the account check and submit. Requesting 500 points puts ₩500 in your account.
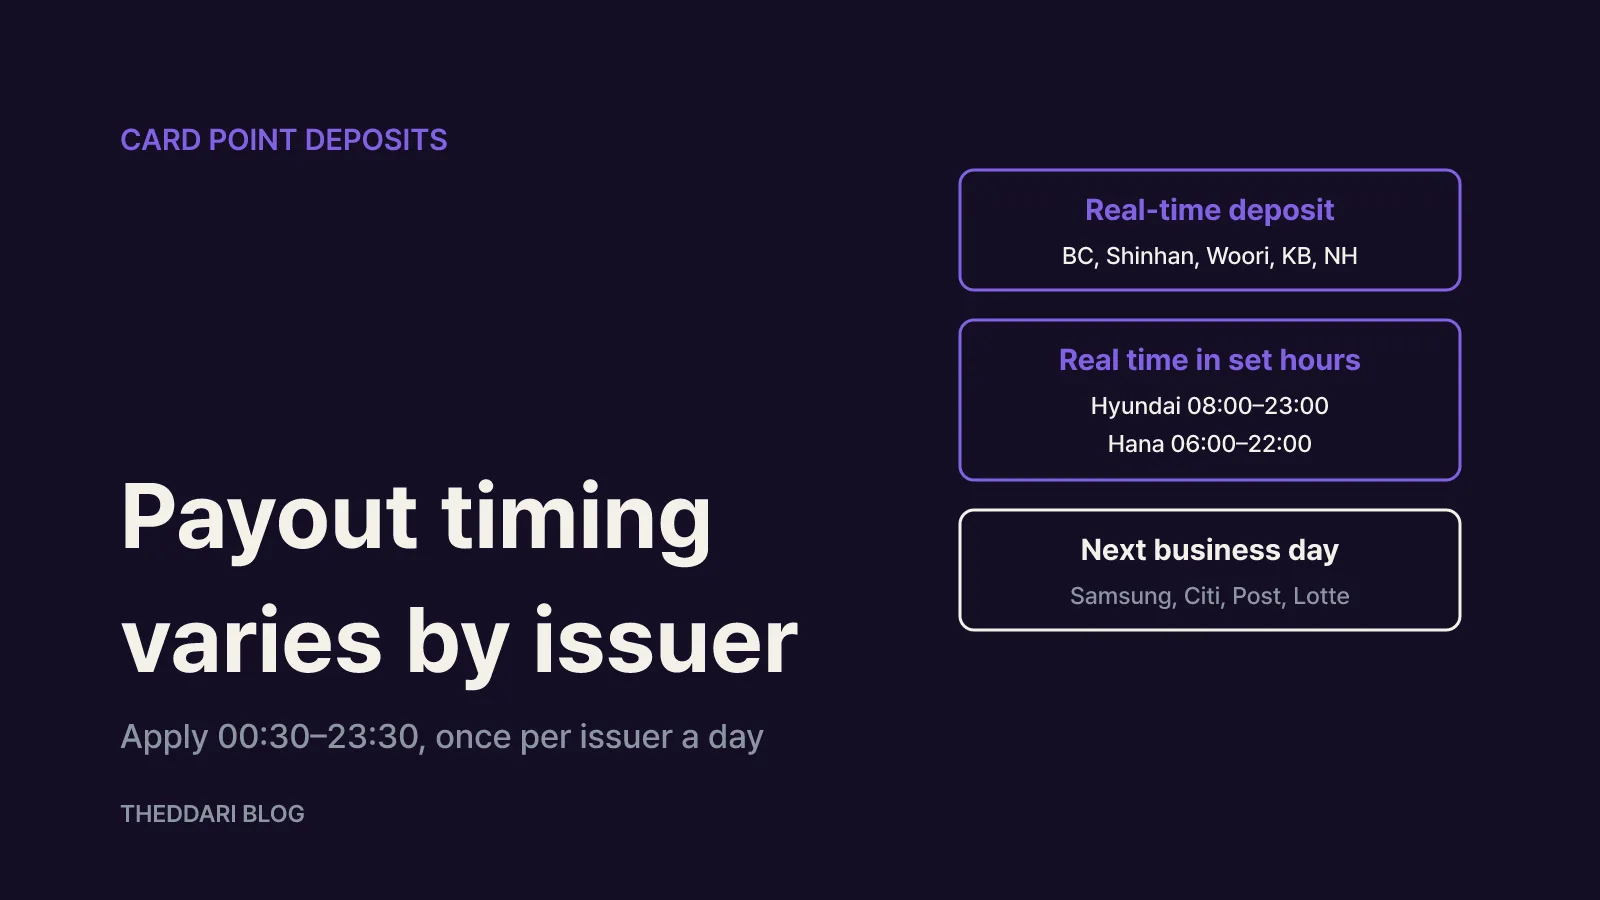
Requests are accepted daily from 00:30 to 23:30; the window from 23:30 to 00:30 is reserved for system maintenance. You can file one request per issuer per day, so bundle everything from the same card company into a single request. The receiving account must be in your own name and pass verification. Accounts in someone else's name, and even your own account if it is frozen or under seizure, will be rejected.
Timing depends on the issuer, according to CREFIA:
- Real time: BC, Shinhan, Woori, KB Kookmin and NH NongHyup
- Real time within set hours: Hyundai (requests made 08:00 to 23:00) and Hana (06:00 to 22:00); requests outside those hours are paid in order at the next real-time window
- Next business day: Samsung, Citi, Korea Post and Lotte
Even when payment lands the next business day, the points are deducted the moment you submit. Completed requests cannot be canceled or corrected; if you want the money turned back into points, you have to ask the issuer directly.
Protect your points before closing a card
Under Article 15(1) of the standard personal credit card terms, remaining points must survive for their validity period even after you close a card, unless you ask the issuer to delete your personal data. Before you fully withdraw as a member or request data deletion, the issuer must tell you how long your points remain valid and how to use them. The practical takeaway: if you plan to leave a card company entirely, or you are leaving Korea, cash out flagship points first.
Article 15(7) also requires issuers to notify you of points scheduled to expire, and when, every month starting six months beforehand, through your billing statement or a similar channel. The FSC notes that this monthly notice was added to the standard terms in December 2014. If you receive statements only by email or push notification, search them for the expiry line rather than waiting for a separate alert.
The stakes are real. FSC figures show ₩117.1 billion in card points expired in 2019, a 3.3% expiry rate against points earned. The FSC explained that expired points had largely ended up as card company revenue.
Avoid cash-out scams and know whom to call
The FSC warns that anyone demanding a fee, your card PIN or CVC to "release" points is likely running a phishing scam. The CREFIA and AccountInfo services are free and never ask for a card password or CVC. Type cardpoint.or.kr into your browser instead of tapping links in text messages.
If a properly submitted deposit has not arrived by the stated deadline, contact the card company, not CREFIA, because the association only relays requests and cannot see what happens afterward. CREFIA's FAQ lists issuer numbers, such as Shinhan 1544-7000, KB Kookmin 1588-1688, Samsung 1588-8700 and Hyundai 1577-6000. Questions about the portal itself go to CREFIA at 02-2011-0700.
A quick year-end routine covers most cases: check balances and expiry months, confirm which programs are flagship points, submit one request per issuer between 00:30 and 23:30 to an account in your own name, and follow up with the issuer if a next-business-day payment does not show up.