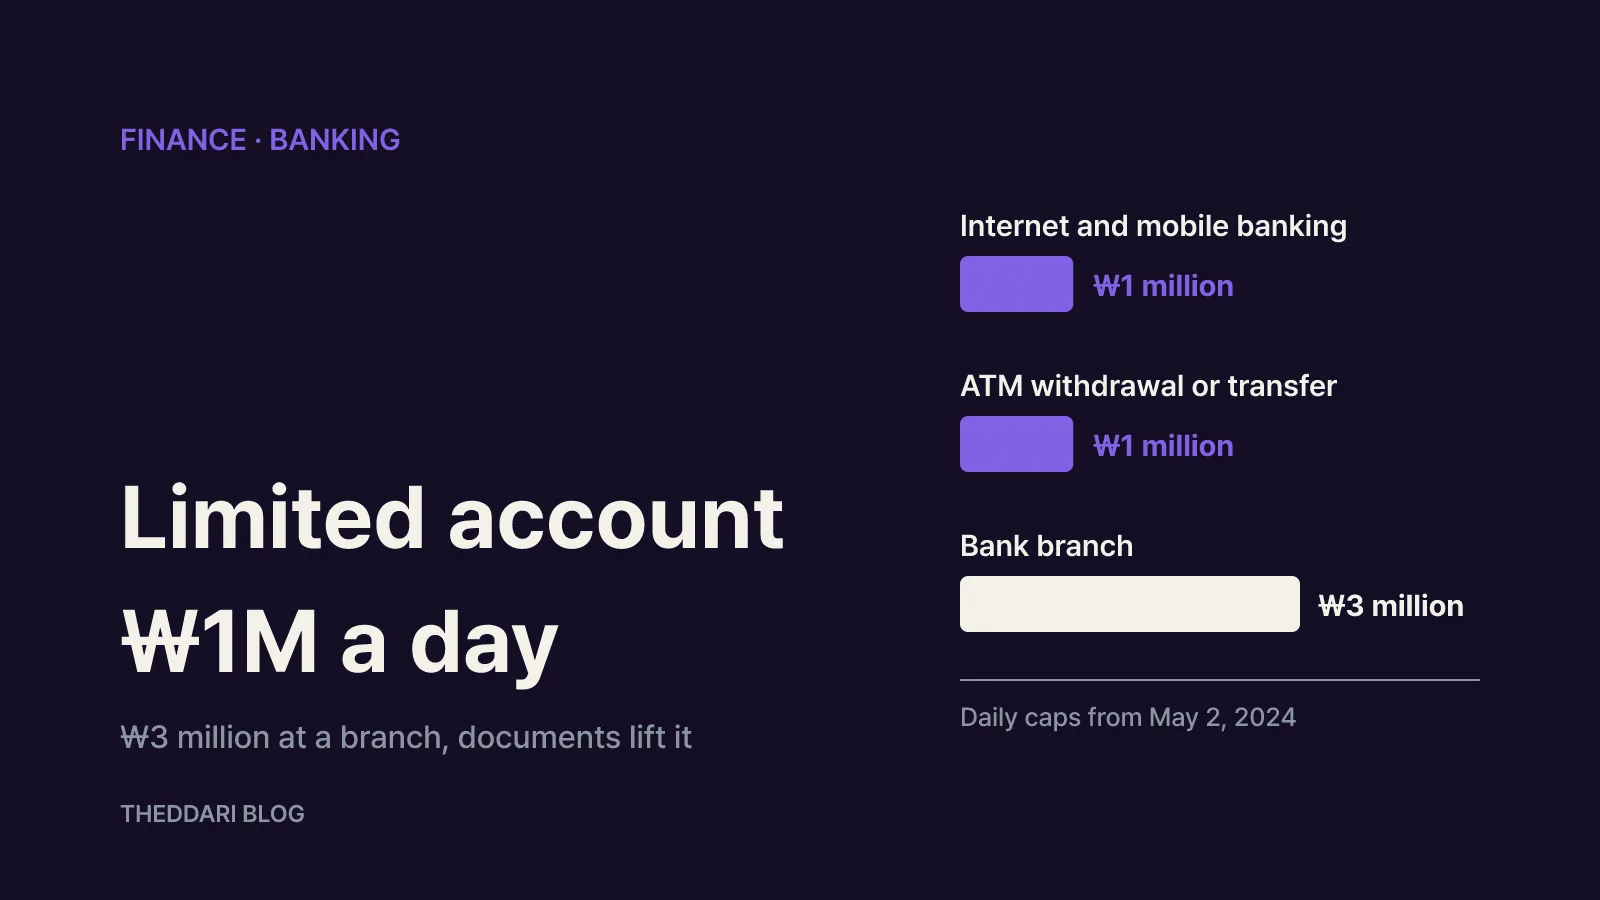
As of November 2026, a South Korean "limited account" (officially a financial transaction limit account, 금융거래한도계좌) lets you move up to ₩1 million per day through internet or mobile banking, ₩1 million per day at ATMs, and ₩3 million per day at a bank branch. These caps took effect on May 2, 2024 under a Financial Services Commission (FSC) press release, and they were applied to existing accounts automatically. To remove the cap entirely, you show the bank what the account is for, such as receiving a salary or a pension, or you meet a bank's own criteria and request removal in its app.
If you are a foreign resident, a student or a freelancer in Korea and your banking app rejected a rent or tuition transfer with a "limited account" message, this guide explains what the cap is, why it applies to you and what evidence Korean banks typically accept.
What are the daily limits on a Korean limited account?
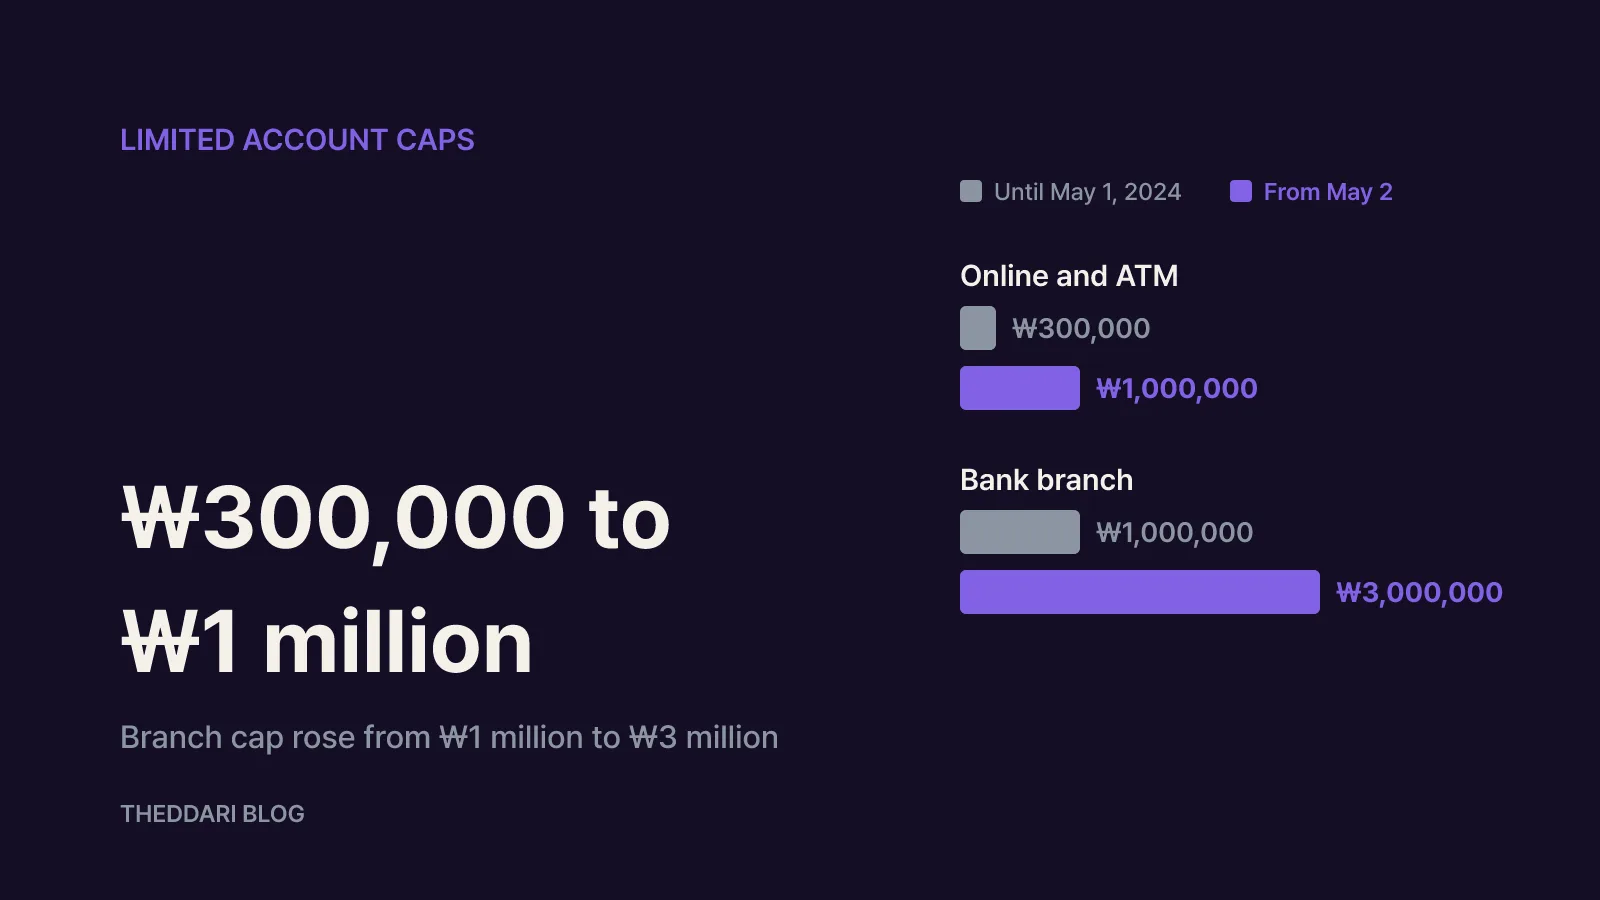
The FSC, the Financial Supervisory Service and the banking sector jointly raised the daily caps. The new figures replaced limits that had been unchanged since 2016.
← Swipe to see more
| Channel | Until May 1, 2024 | From May 2, 2024 |
|---|---|---|
| Bank branch (teller) | ₩1,000,000 | ₩3,000,000 |
| ATM withdrawal | ₩300,000 | ₩1,000,000 |
| ATM transfer | ₩300,000 | ₩1,000,000 |
| Internet and mobile banking | ₩300,000 | ₩1,000,000 |
A few exceptions matter in practice:
- Start dates varied slightly. NongHyup, Hana and Busan Bank applied the higher caps on May 10, 2024. Mutual and cooperative lenders, including Suhyup, credit unions, Saemaul Geumgo and the Korea Post bank, were scheduled to follow by August 28, 2024.
- Internet-only banks kept their earlier caps. According to the FSC, limited accounts at internet-only banks remain at ₩1–2 million for ATM and electronic transactions.
- Opting out was possible. Customers who did not want the automatic increase could ask their bank to keep the old caps.
- Older accounts may differ. KB Kookmin Bank's guide says the raised caps apply retroactively to limit accounts opened on or after March 2, 2016, while KB accounts opened on or before March 1, 2016 keep their earlier ₩700,000 caps for ATM and online transfers. At other banks, check the account detail screen in the app.
The caps are set per channel, not as one total for the account. Whether a branch withdrawal is still possible after you have used your mobile allowance for the day is something to confirm with the teller.
Why was my account opened as a limited account?
Since 2012, Korean banks have been required to confirm the purpose of a new demand-deposit account to stop "burner" accounts (대포통장) that criminals rent or buy for phone scams. People who could not provide objective evidence of a purpose often could not open an account at all. The limited account, introduced in 2016, was the compromise: you get a working account, but with low daily caps. It is a fraud safeguard, not a judgement about your credit.
Common triggers include:
- Opening an account without employment documents, which is typical for homemakers, students and newly arrived residents
- Opening an account online without completing the purpose-verification step
- Changing jobs and being unable to show current salary evidence
Limits can also be tightened. Since March 29, 2024, an account that was used in a fraud case can have its withdrawal and transfer caps cut back to the old levels of ₩300,000 online, ₩300,000 at ATMs and ₩1 million at a branch, even after the payment suspension on the account is lifted. The standard deposit terms were amended to list reduced limits as a possible restriction. Never lend or sell your bankbook or debit card to anyone.
Documents that prove your account's purpose
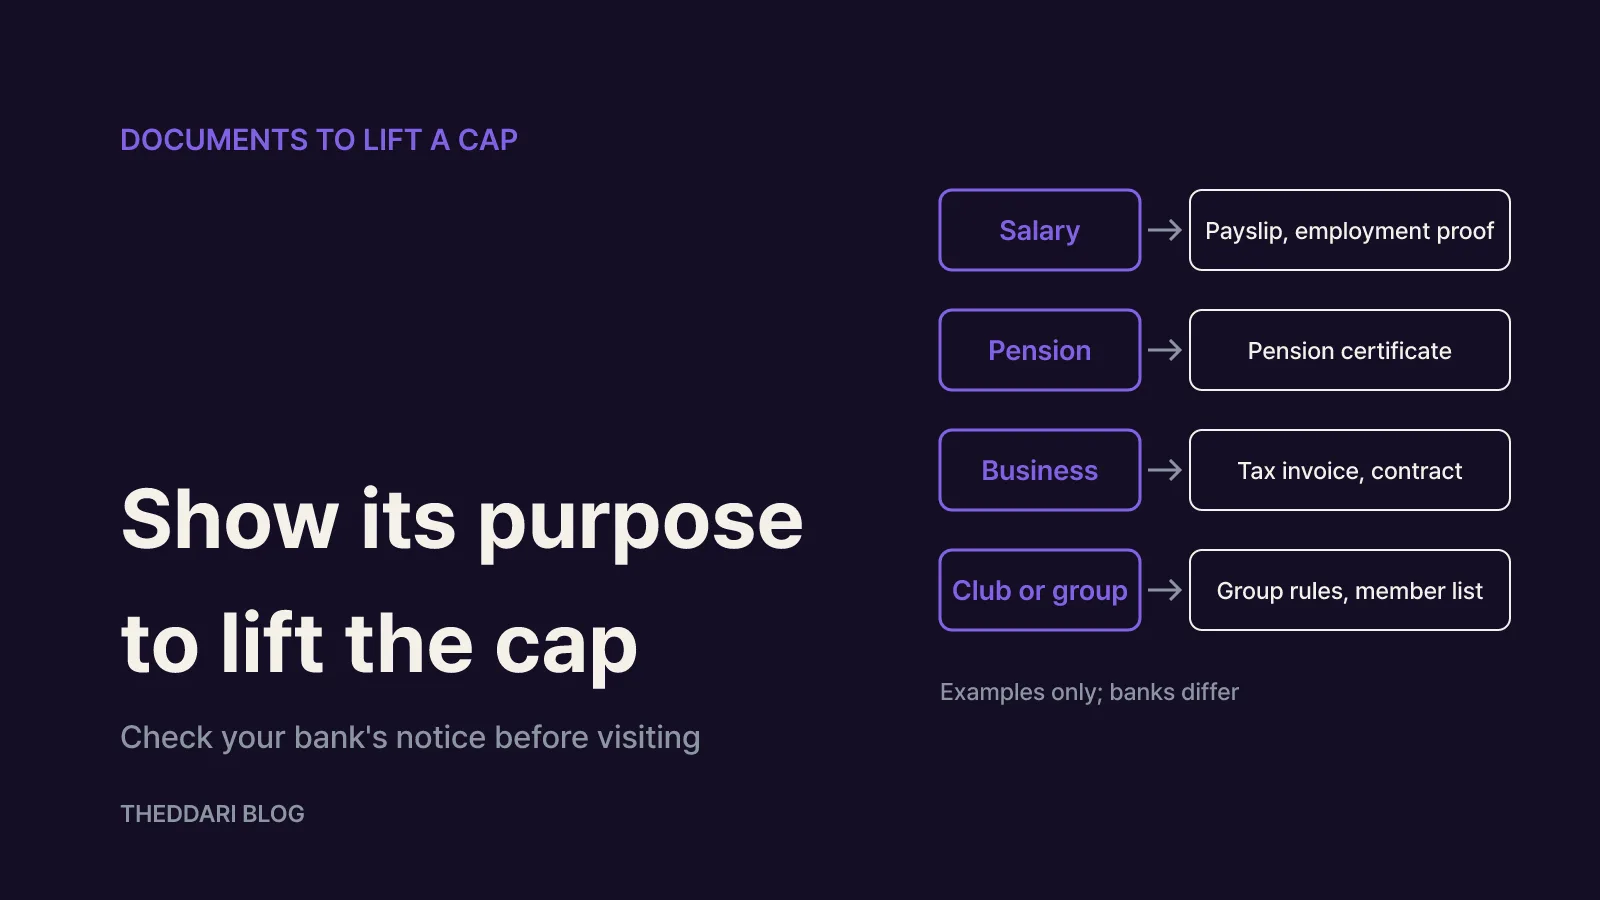
To lift the cap, the bank wants to know what the account is used for. The FSC asked banks to post notices in branches and on their websites listing typical documents for each purpose. Its examples were a health insurance qualification certificate or an earned-income withholding receipt for salary accounts, and a pension certificate for pension accounts. Combined with KB Kookmin Bank's examples:
← Swipe to see more
| Account purpose | Example documents |
|---|---|
| Salary | Certificate of employment, payslip, earned-income withholding receipt, health insurance qualification certificate |
| Pension | Pension certificate or proof of entitlement |
| Business | Supply contract, (electronic) tax invoice, financial statements, VAT certificate, tax payment certificate |
| Club or group | Member list, group rules |
| Utilities or building fees | Utility payment receipts, management fee receipts |
| Other | Any objective evidence of the account's purpose |
Keep three points in mind:
- The list is illustrative. The FSC says customers may submit other evidence and banks may ask for more. KB notes that a branch can still decline a request after reviewing documents.
- Requirements vary by bank. Read your bank's posted notice before visiting.
- Public MyData can replace paperwork. With your consent, a bank can collect purpose-related information, such as your workplace, automatically, which reduces the number of paper documents you need. Ask whether your branch supports this.
Lifting the limit online without a branch visit
Some banks accept removal requests in their apps if you meet set conditions. At KB Kookmin Bank, customers aged 15 or older qualify if any one of these applies:
- Customer tier: a KB Star Club tier of VVIP, VIP or Grand
- Salary deposits: salary transfers of ₩1.5 million or more per payment for three consecutive months, as of the end of the previous month
- Pension deposits: National Pension, civil service, private school teachers', military or veterans' pension payments of ₩500,000 or more per payment for the last three consecutive months
- Linked trading: stock trading through a KB able Plus account
In the KB Star Banking app, open the full account list, tap the menu next to the limited account and choose the option to request removal of the limit. These criteria are KB-specific. Other banks use their own periods and thresholds, so check your bank's app.
A step-by-step checklist before you apply
- Check your current cap in the account details of your banking app. Internet-only banks and accounts opened before 2016 may follow different numbers.
- Split today's payment by channel. If you need more than ₩1 million, decide whether the ₩3 million branch allowance or several days of transfers will cover it.
- See whether you already qualify online. If your salary or pension already lands in the account, an app request may be the fastest route.
- Prepare purpose documents based on your bank's notice, and ask whether MyData consent can replace any of them.
- Visit a branch with your ID and bring supporting papers in case the bank asks for more.
Anyone offering to lift your limit for a fee, or asking to borrow your account to build transaction history, is running a scam. Removal is only done by you, directly with your own bank.